
Executive Condos (ECs): A Buyer’s Guide (2026)
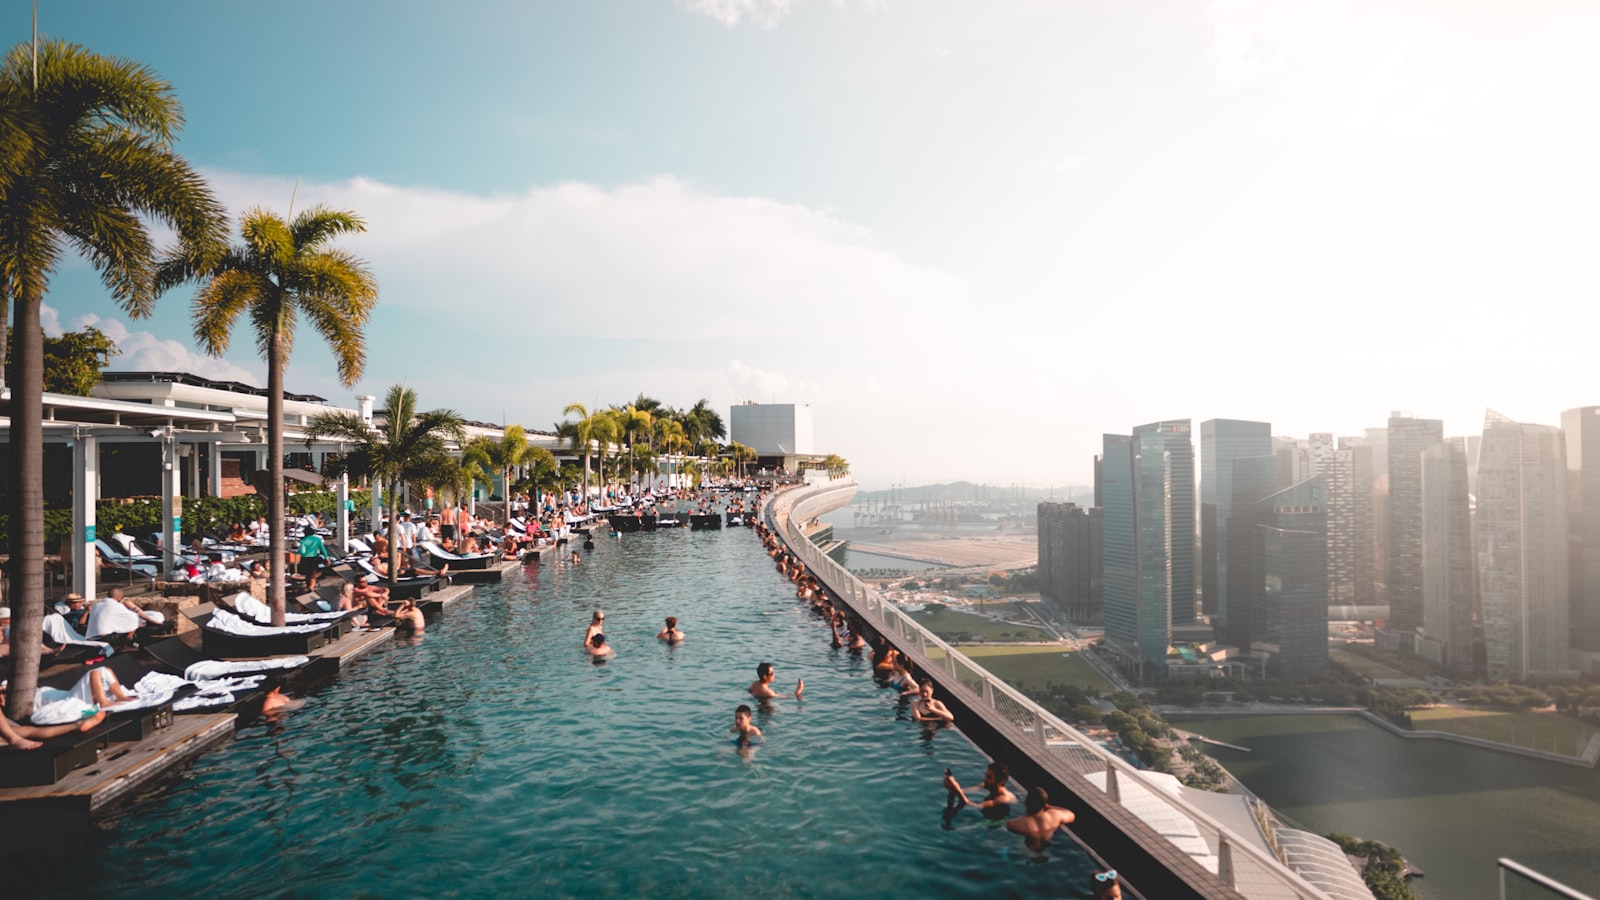
Somewhere between the HDB heartlands and full private condominium living sits one of Singapore’s most distinctive housing inventions: the executive condominium. An EC looks like a private condo — pool, gym, security, balconies — but is sold new under public-housing-style rules at a discount to comparable private projects. For the right buyer, that combination is the sweet spot of the entire market. For the wrong one, the restrictions become handcuffs. This guide explains how to tell which buyer you are.
What an EC actually is
Executive condominiums are developed and sold by private developers on land sold through government tender, but the government attaches conditions to who may buy them new. The result is a genuine hybrid: full condo facilities and strata living, priced below equivalent private launches because the eligible buyer pool is deliberately restricted.
The magic ingredient is time. An EC starts life as quasi-public housing and ends it as fully private property. That transformation, which completes ten years after the project is finished, is what draws buyers who see ECs as private condos bought at a structural discount.
Who can buy a new EC
Buying a new EC from a developer means clearing HDB-style eligibility gates. In broad terms, you must include a Singapore citizen and apply under an eligible family nucleus (with schemes covering couples, families and, under some conditions, singles combining), your household income must fall under the EC income ceiling, and you must not hold other property or must dispose of it within the required window. The exact income ceiling and scheme details shift over time, so verify the current figures on HDB’s website before planning around them.
Two more gates matter. Buyers who previously enjoyed a housing subsidy may need to pay a resale levy, and everyone signs up to a minimum occupation period after completion. If you have already owned subsidised housing twice, new ECs are off the table entirely.
The money side: bank loans only
Financing is where ECs surprise people. Despite the HDB-flavoured eligibility, you cannot take an HDB loan for an EC — bank financing is the only route, which means bank loan-to-value limits and a compulsory cash component in the downpayment. Progressive payment schemes during construction (or deferred payment options some developers offer) shape your cash flow, and stamp duties apply as with any property purchase — our explainer on BSD and ABSD stamp duties covers what to budget.
Eligible first-timer households may receive CPF housing grants on new ECs, tiered by income — again, check current grant conditions rather than assuming figures you have seen quoted. The practical takeaway: an EC purchase needs stronger upfront cash planning than a BTO, even though the eligibility paperwork feels similar.
MOP, privatisation and the ten-year arc
Every new EC comes with a five-year minimum occupation period from completion, during which you must live in the unit and cannot sell it or rent out the whole flat. After the MOP, you may sell — but only to Singapore citizens and permanent residents, which limits the buyer pool.
The full transformation lands at year ten, when the project privatises completely and units can be sold to foreigners and companies like any private condo. That widened demand pool is the engine behind the EC value thesis, and it is why many owners hold past the MOP to the privatisation milestone. The mechanics of MOP rules more broadly are covered in our guide to how the minimum occupation period works.
EC vs BTO vs private condo
Against a BTO flat, an EC buys you facilities, gated grounds and the privatisation runway — at a substantially higher price, bank-loan cash requirements and condo maintenance fees for life. Against a private condo, a new EC typically costs meaningfully less per square foot for comparable newness, in exchange for eligibility hoops, the MOP and resale restrictions in the early years.
Location is the quiet variable: EC sites are usually in non-central areas, so you are often comparing a further-out EC against a more central resale condo at similar money. If you are weighing the private route seriously, our guide on how to buy a condo in Singapore walks through that process, and remember that ongoing costs differ too — condo-style maintenance fees apply to ECs from day one.
Resale ECs: a different product
Buying an EC on the resale market after its MOP is a much simpler transaction: no income ceiling, no family nucleus requirement, citizens and PRs eligible (and anyone, once fully privatised). Prices reflect that freedom. Post-MOP ECs in good locations behave essentially like private condos with a slightly younger legal history, and they can be a pragmatic middle path for buyers who miss new-launch eligibility.
Questions to ask before committing
Run yourself through this list honestly. Can you comfortably fund a bank-loan downpayment with the required cash? Will your household still fit the unit five-plus years from now, given the MOP locks you in? Does the EC’s location serve your actual commute, or only its price point? Have you verified the current income ceiling, grant tiers and resale levy rules on HDB’s site? And if privatisation upside never materialises, would you still be happy living there? An EC should pass the home test before the investment test.
A decision framework: eligibility, budget, timeline, restrictions
When the EC-versus-BTO-versus-private-condo question refuses to resolve itself, run the three options through four filters in order. Eligibility first: if your household income exceeds the EC ceiling, the choice collapses to private property; if you cannot form an eligible family nucleus or have used your subsidised-housing chances, new ECs and BTOs both drop out. Budget second: a BTO needs the least cash upfront and can run on an HDB loan; an EC demands a bank-loan cash downpayment plus progressive payments; a private condo costs the most per square foot with the same bank-only financing. Be honest about cash on hand, not just monthly affordability.
Timeline third: all three new-launch routes involve multi-year construction waits, but the lock-ins differ — a BTO or EC ties you down through its minimum occupation period, while a resale private condo can be sold or rented out whenever life demands it. If a job move abroad or family change within five to seven years is plausible, that flexibility is worth real money. Restrictions last: if you clear the first three filters and can genuinely live with the MOP, the EC’s structural discount usually makes it the strongest value of the three; if any filter pinches, the cheaper certainty of a BTO or the freedom of private property is the better trade.
What the privatisation timeline means in practice
The five- and ten-year milestones are not just legal footnotes — they should shape how you plan the ownership arc before you sign. During the MOP, treat the EC as illiquid: you live in it, full stop, so your emergency-cash planning cannot assume selling the unit. At year five, the door opens partially — you can sell to citizens and PRs, or rent out the whole unit — and some owners exit here if life has moved on, accepting a buyer pool that excludes foreigners.
Year ten is where the original thesis pays out or does not: full privatisation adds foreign and corporate buyers to the demand pool, which is why many owners deliberately hold the extra five years past MOP before selling. Practically, that means the EC suits households who can commit to roughly a decade in one place from completion. If you are buying with a shorter horizon, price in the possibility of selling into the narrower post-MOP market instead — and remember that privatisation widens who can buy, but the price you achieve still depends on location, condition and the market of the day, none of which the milestone controls.
The bottom line
ECs offer private-condo living at a discount, paid for with eligibility rules, bank-only financing and a decade-long path to full privatisation. For income-ceiling-eligible families with solid cash flow and a long horizon, they remain one of the most compelling products in Singapore housing; for buyers who need flexibility soon, the restrictions outweigh the discount. Find more buying guides on our Property & Rentals hub — and if you are ready to compare current EC launches and post-MOP resale options, get matched with a licensed property agent below.
Frequently asked questions
What exactly is an executive condominium?
A hybrid housing type: a full-facility condominium built and sold by private developers, but with government-set eligibility conditions for new buyers, including citizenship, family nucleus and an income ceiling. Check HDB for the current criteria.
Can I use an HDB loan to buy an EC?
No. ECs must be financed with a bank loan (plus cash and CPF), even when bought new under HDB eligibility rules. Budget for the cash downpayment component a bank loan requires.
When can I sell my EC?
After the 5-year minimum occupation period you can sell to Singapore citizens and PRs. From the 10-year mark the project is fully privatised and can be sold to foreigners, which typically widens the buyer pool.
Are ECs a good investment?
Historically many ECs have narrowed the price gap with private condos after privatisation, but past patterns are not guarantees. Treat an EC first as a home whose restrictions you can live with, and any upside as a bonus.
Who is eligible to buy a new executive condominium in Singapore?
In broad terms, the household must include a Singapore citizen, apply under an eligible family nucleus, fall under the EC income ceiling, and not hold other property or dispose of it within the required window. Verify the current income ceiling on HDB's website.
What is the difference between an EC and a BTO flat?
An EC offers condo facilities, gated grounds and a privatisation runway, but costs substantially more than a BTO flat. It needs a bank loan with a cash downpayment, since HDB loans are not allowed, and carries condo maintenance fees from day one.
When does an executive condominium become fully private?
An EC becomes fully private ten years after the project is finished. Before then, a five-year minimum occupation period applies, after which the unit can be sold only to Singapore citizens and permanent residents. After privatisation, it can be sold to foreigners and companies.
Can I buy a resale EC without meeting the income ceiling?
Yes. Buying a resale EC after its MOP involves no income ceiling and no family nucleus requirement. Citizens and PRs are eligible, and anyone once the EC is fully privatised, so it can be a pragmatic middle path for buyers who miss new-launch eligibility.
Speak to a property agent
Looking to rent or buy? We’ll connect you with a licensed agent for your area and budget.
More in Property & Rentals
See all
HDB Buying Jargon: A Glossary for First-Timers (2026)
Confused by HDB jargon? This plain-English glossary explains BTO, MOP, OTP, HFE, COV, EIP, CPF grants and more so first-time flat buyers…

Suburban vs City HDB Living: Which Suits You? (2026)
Suburban vs city HDB living in Singapore: compare price, space, commute, MRT access, amenities and BTO supply so you can pick the…
HDB Eligibility Schemes and the Family Nucleus (2026)
Understand HDB eligibility schemes and the family nucleus rule: the Public, Fiance/Fiancee, Single and Joint Singles routes to buying an HDB flat.