
HDB BTO vs Resale: Which Should You Buy? (2026)
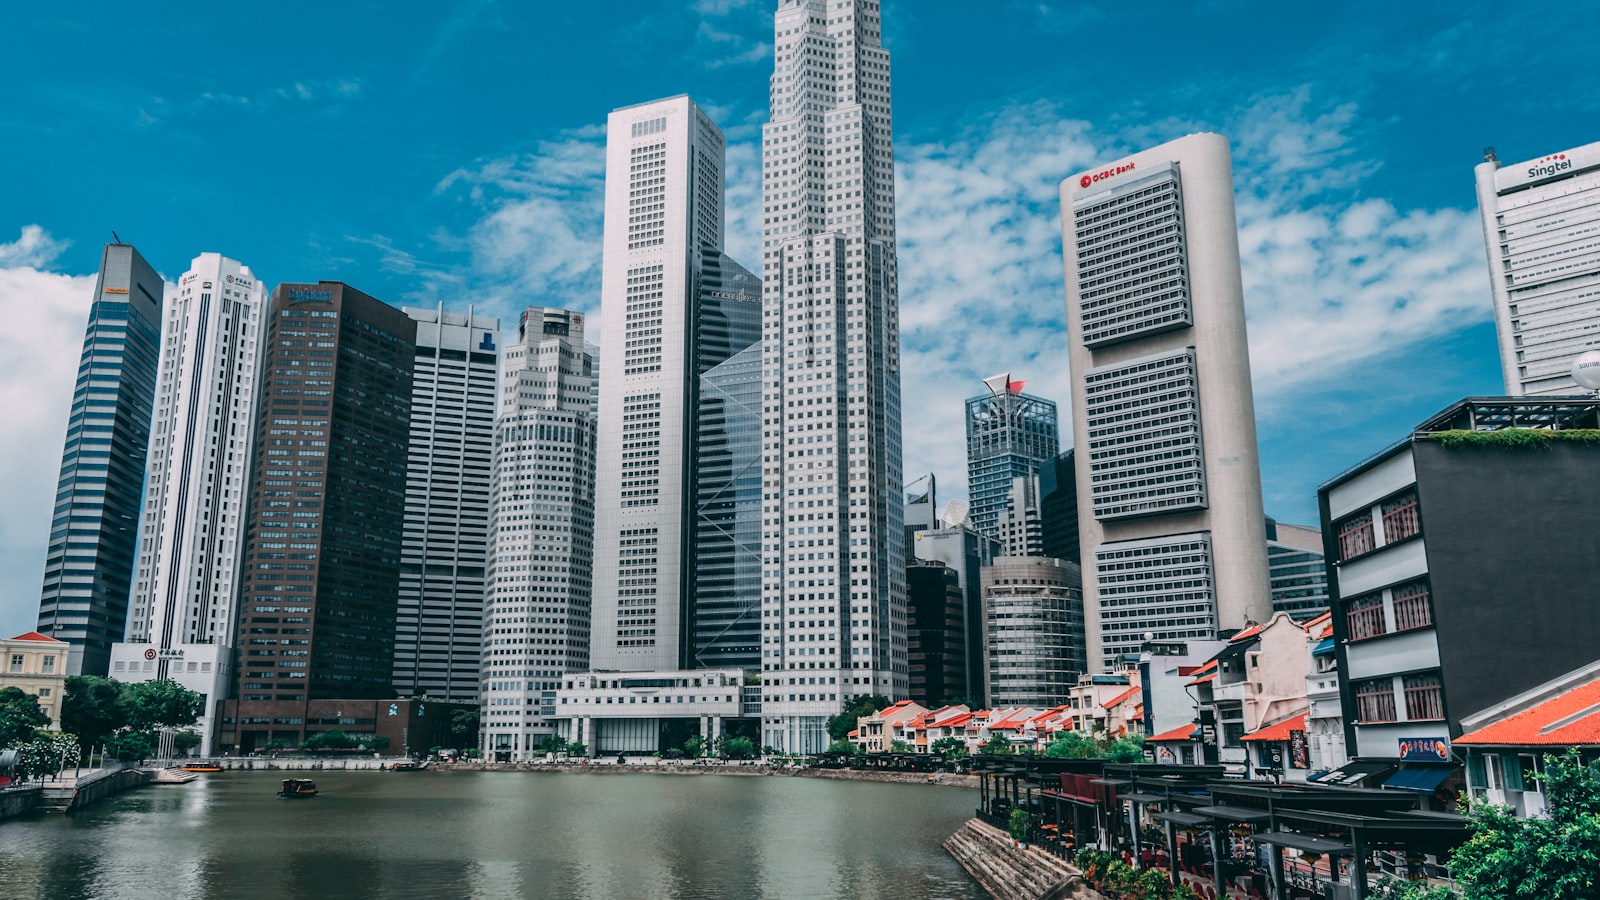
Buying your first flat in Singapore almost always comes down to one fork in the road: apply for a brand-new BTO and wait, or buy a resale flat on the open market and move in sooner. Both are HDB homes, but they behave very differently on price, timing, location and the rules that come attached. Getting this decision right shapes your finances for the next decade, so it’s worth slowing down and comparing them properly.
What “BTO” and “resale” actually mean
A BTO (Build-To-Order) flat is a new home you buy directly from HDB. HDB launches projects in sales exercises, and construction only ramps up once enough units are booked, which is why there’s a waiting period. In 2026, BTO flats are sold under a classification of Standard, Plus or Prime, which replaced the older mature/non-mature estate split. Standard flats have the usual conditions; Plus and Prime flats sit in choicer or more central locations, come with extra subsidies, and in return carry tighter resale restrictions and a subsidy clawback when you eventually sell.
A resale flat is an existing HDB flat you buy from another owner on the open market. There’s no waiting to build and no balloting — you shop, negotiate, and if the seller agrees, you transact. You’ll pay closer to market value, but you get certainty on the exact unit, floor and estate.
Price: cheaper up front vs pay for certainty
On paper, BTO flats are the cheaper option because HDB prices them below comparable resale units. That’s the headline advantage. But the true cost gap narrows once you account for the years you’d otherwise spend renting or living with family while a BTO is built.
Resale prices vary enormously by town, flat type, floor and remaining lease. As a rough guide, expect resale flats to command a meaningful premium over an equivalent new BTO in the same area — but you’re buying time and a known quantity. If you’re weighing a resale purchase against renting in the meantime, our guide on HDB vs condo rental costs can help you frame the “wait and rent” side of the maths.
Waiting time and life stage
This is often the deciding factor. A BTO typically takes around 3–4 years to complete, though HDB has offered some shorter-wait projects and balance flats with quicker timelines. If you’re getting married soon, planning children, or simply can’t stay put for three or four years, that wait matters more than a few thousand dollars of savings.
A resale flat, by contrast, can have you holding keys within a few months of a successful application. For couples on a tight timeline, buyers who need a specific school zone now, or multi-generational families who want to live near relatives immediately, resale often wins on timing alone.
Location and lease
BTO launches are limited to wherever HDB is building that quarter, so your location choice is constrained by the sales exercise. Resale opens up the entire island — every mature town, every established neighbourhood with amenities already in place.
The trade-off is lease. A new BTO starts with a fresh 99-year lease. A resale flat has a shorter remaining lease, which affects how much CPF you can use and the loan you can get, especially if the remaining lease is short relative to the youngest buyer’s age. Always check the remaining lease before falling in love with a resale unit.
Grants and financing
Eligible first-timer resale buyers can stack several CPF Housing Grants — the Enhanced CPF Housing Grant (EHG), the Family Grant, and the Proximity Housing Grant (PHG) if you buy near your parents or children. These can materially close the price gap with a BTO. BTO buyers may qualify for the EHG too, but the flat is already subsidised, so the grant landscape differs.
Whichever route you take, you now need an HDB Flat Eligibility (HFE) letter before applying for a flat or an HDB housing loan. The HFE consolidates your eligibility to buy, your grant entitlement and your loan eligibility in one place. You’ll also choose between an HDB loan (requires the HFE) and a bank loan. Grant amounts and eligibility change over time, so treat any figure you read online as approximate and verify current entitlements directly with HDB.
Rules to read before you commit
Both routes carry a Minimum Occupation Period (MOP) — generally five years before you can sell or rent out the whole flat. Plus and Prime BTO flats add restrictions: a longer effective holding commitment in practice, resale limited to eligible buyers, a possible rental cap on the whole unit, and a subsidy clawback (a percentage of the resale price returned to HDB) when you sell. Standard flats and most resale flats don’t carry the clawback, which can make resale simpler if you value flexibility.
Buying resale also means a different transaction process — valuation, possible Cash-Over-Valuation (COV), Option to Purchase, and appointing a licensed salesperson. Our step-by-step resale HDB guide walks through each stage, and if you’re a first-timer weighing eligibility schemes and grants, the first-time HDB buyer’s guide covers the essentials.
Who should choose which
Lean BTO if: you can wait 3–4 years, you want the lowest entry price and a fresh 99-year lease, and you’re comfortable with the location options in current launches. It rewards patience and planning.
Lean resale if: you need to move soon, you want a specific mature estate or floor, you value a settled neighbourhood with amenities in place, or you can unlock enough grants to make the numbers work. It rewards certainty and speed.
Many buyers also compare HDB against private property at this stage. If that’s you, our comparison of condo vs HDB lays out the trade-offs on budget, financing and lifestyle.
A quick side-by-side
To pull it together, here’s how the two stack up on the factors that usually decide it:
- Price: BTO lower on the sticker; resale higher but grants can narrow the gap.
- Wait: BTO roughly 3–4 years to keys; resale a few months.
- Location: BTO limited to current launches; resale opens the whole island.
- Lease: BTO fresh 99 years; resale a shorter remaining lease that affects CPF and loan.
- Rules: both carry a 5-year MOP; Plus and Prime BTO flats add resale limits and a clawback.
Run your own situation through that list before deciding — the “right” answer changes person to person.
It also helps to think a step beyond the purchase. A BTO in a newer town means you are buying into an estate that is still maturing: amenities, transport links and the community all fill in over the years you live there, which can be exciting but occasionally inconvenient at first. A resale flat in a mature estate gives you a settled neighbourhood from day one, with schools, markets, clinics and MRT already in place. Consider too how each choice ages: a fresh 99-year lease preserves the flat’s value and financing options far into the future, while a resale flat with a shorter remaining lease may be harder to sell or finance down the line, so match the lease to how long you realistically plan to stay.
The bottom line
BTO vs resale isn’t about which is objectively better — it’s about which fits your timeline and budget. BTO saves money if you can afford to wait; resale saves time and gives you certainty if you can’t. Map out your move-in deadline, get your HFE letter early, tally the grants you actually qualify for, and read the specific conditions on any Plus or Prime flat before you sign anything. Verify all current prices, grants and rules with HDB, since they change.
Not sure which route suits your situation, or want help shortlisting resale units and understanding the numbers? Get matched with a licensed property agent through the form below.
Frequently asked questions
Is a BTO always cheaper than a resale flat?
Usually yes on the sticker price, because BTO flats are priced below the open market. But a resale flat can be better value once you factor in the years you save on rent while waiting, plus grants you may qualify for. Compare total cost, not just the launch price.
How long is the wait for a BTO in 2026?
As a rough guide, most BTO projects take about 3–4 years to complete, though HDB has launched some shorter-wait and balance flats. Check the estimated completion date on each specific launch before you commit.
Can I get housing grants for a resale flat?
Eligible first-timers buying resale can apply for grants such as the Enhanced CPF Housing Grant, the Family Grant and the Proximity Housing Grant. Amounts depend on income, flat type and who you live near, so verify your entitlement with HDB.
What is the MOP and does it differ for Plus and Prime flats?
The Minimum Occupation Period is generally five years before you can sell. Plus and Prime flats can carry additional resale restrictions and a subsidy clawback, so read the specific conditions attached to your flat.
Speak to a property agent
Looking to rent or buy? We’ll connect you with a licensed agent for your area and budget.
More in Property & Rentals
See all
HDB Buying Jargon: A Glossary for First-Timers (2026)
Confused by HDB jargon? This plain-English glossary explains BTO, MOP, OTP, HFE, COV, EIP, CPF grants and more so first-time flat buyers…

Suburban vs City HDB Living: Which Suits You? (2026)
Suburban vs city HDB living in Singapore: compare price, space, commute, MRT access, amenities and BTO supply so you can pick the…
HDB Eligibility Schemes and the Family Nucleus (2026)
Understand HDB eligibility schemes and the family nucleus rule: the Public, Fiance/Fiancee, Single and Joint Singles routes to buying an HDB flat.